
How Semiliquid Managers Can Hide Fees
Incentive fees are occasionally disclosed but continuously collected.

Investors looking at semiliquid funds are in for sticker shock, especially if they are accustomed to low-cost exchange-traded funds and mutual funds. A key structural difference in the fees attached to semiliquid funds is that they make frequent use of incentive (also called performance) fees.
An incentive fee should be conditional, meaning it should only be earned by fund managers if their actions directly lead to a positive outcome. Unfortunately, because of their structures, semiliquid funds’ incentive fees are effectively unconditional and virtually always collected regardless of whether the manager acted prudently or not. On top of that, asset managers play coy about how predictable the fees are, leading to inconsistent disclosures that make apples-to-apples fee comparisons more difficult than they need to be.
In a recently published report, I documented all the issues with incentive fee structures and their disclosure practices in semiliquid funds. I offer a few suggestions on how to improve them and why investors need to care about them. Below highlights two of the problems, particularly as they relate to private credit, one of the booming asset classes in semiliquid structures.
Problem 1: Lack of Consistent Disclosure
In almost every investment ad, investors are told to “consider the investment objectives, risks, charges, and expenses carefully before investing,” or some similar directive. This is the fund company’s (legally obligated) way of encouraging investors to actually read the prospectus of a fund before investing in it.
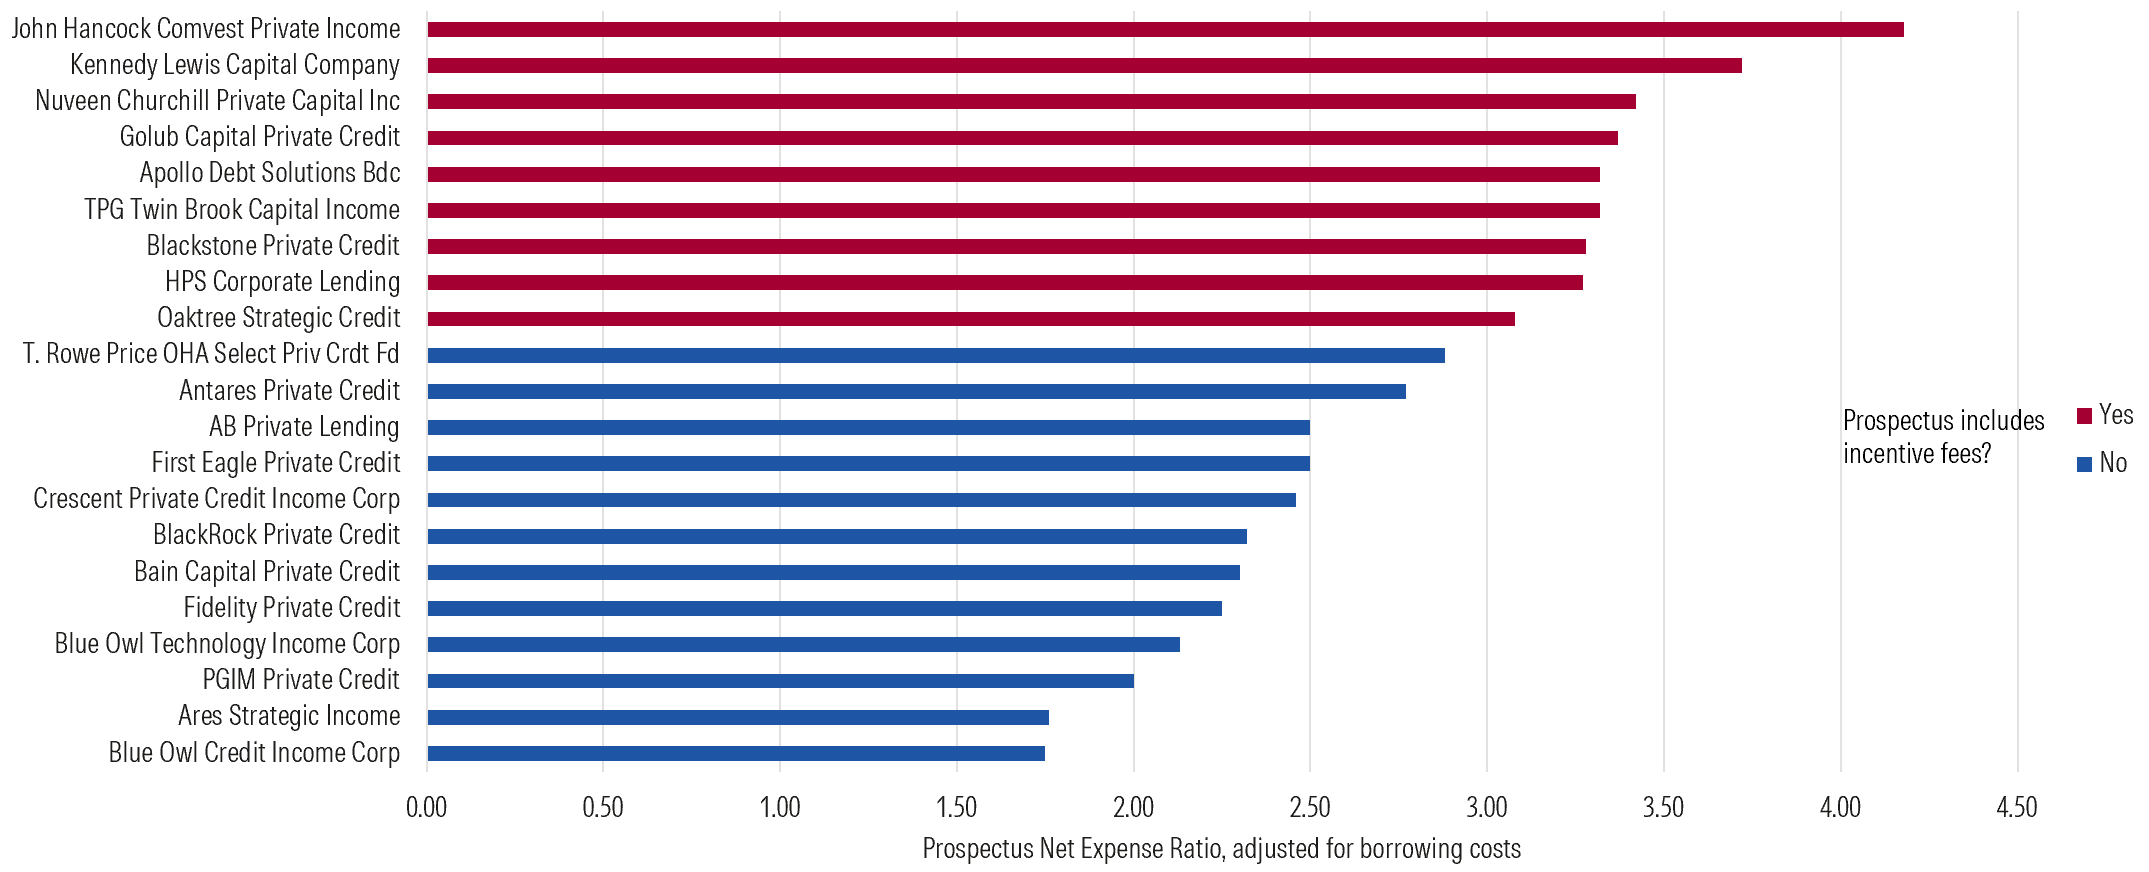
But what if the prospectus itself is misleading? In semiliquid funds, that is often the case. Many of these funds, particularly unlisted business-development companies, charge incentive fees but do not actually include them in their prospectus fee tables. Why? They almost all use the same language: “As we cannot predict whether we will meet the necessary performance targets, we have assumed no incentive fee for this chart.”
Since these fees are allegedly unpredictable, they can be excluded from prospectus expense ratios. Yet, not all semiliquid funds consider these fees to be uncertain. In fact, funds with identical fee structures oftentimes show different prospectus net expense ratios, even after adjusting for leverage and other ancillary costs, all thanks to each fund’s treatment of incentive fees.
Identical Fee Structures but Nonidentical Fee Tables
For example, the above chart shows Blue Owl Credit Income and Blackstone Private Credit’s adjusted net expense ratios from their latest prospectuses (left) and annual reports (right). If investors were just to look at the two prospectuses’ fee tables, they could conclude that Blue Owl’s annual expense ratio is a lot lower after backing out borrowing costs (as Morningstar does when adjusting expense ratios). But clearly, as the annual report’s expense data shows, the fees are basically the same, since the annual report contains the realized incentive fees incurred. The lesson is simple: Looking at prospectus fee ratios alone can lead investors astray.
Yet Blue Owl is not alone; more than half of unlisted BDCs do not include incentive fees in their prospectuses despite almost always collecting them and having nearly uniform fee structures.
Despite Highly Similar Fee Structures, Unlisted BDC Prospectus Fees Vary Significantly
Problem 2: What Exactly Is the Incentive?
Do the asset managers have a case on the unpredictability of the fees? Perhaps in equity-focused portfolios, but almost certainly not in private credit.
Semiliquid private credit funds generally lend money at floating rates, meaning they lend at a spread above a reference interest rate, like the Secured Overnight Financing Rate. Their incentive fee, however, is based on a fixed “hurdle rate,” which is the rate that the fund’s return needs to clear before collecting incentive fees. However, these private credit funds typically lend at spreads at or above their hurdle rates, thus ensuring near-continuous incentive fee collection.
This mismatch of a floating lending rate and fixed hurdle rate thus creates a scenario where it takes extraordinary circumstances for a private credit fund not to collect its incentive fee, especially given the prevalent use of leverage, which boosts the lending yields.
For example, the table below shows the percentage of the maximum possible incentive fees a fund would have collected under different interest rate and leverage scenarios. It assumes the typical unlisted BDC fee structure (which uses a 5% hurdle rate) and that the fund lends at a weighted average spread of 5.5% over reference interest rates (like SOFR) and borrows at a 2.0% spread. At 40% leverage (that is, 40% of the fund’s overall capital is borrowed), the fund doesn’t need reference rates to be above zero to earn full incentive fees. That is not asking much, as the typical unlisted BDC operates at 45% leverage, and very few are under 40%. Interval funds cannot exceed 33.3% by law, but at maximum leverage, they are close to maxing out their incentive fees even with zero interest rates. When base interest rates are 2% or higher, clearing the hurdle is a virtual guarantee, no matter the leverage amount.
Percentage of Maximum Possible Incentive Fees Earned by Base Rate and Leverage Scenario
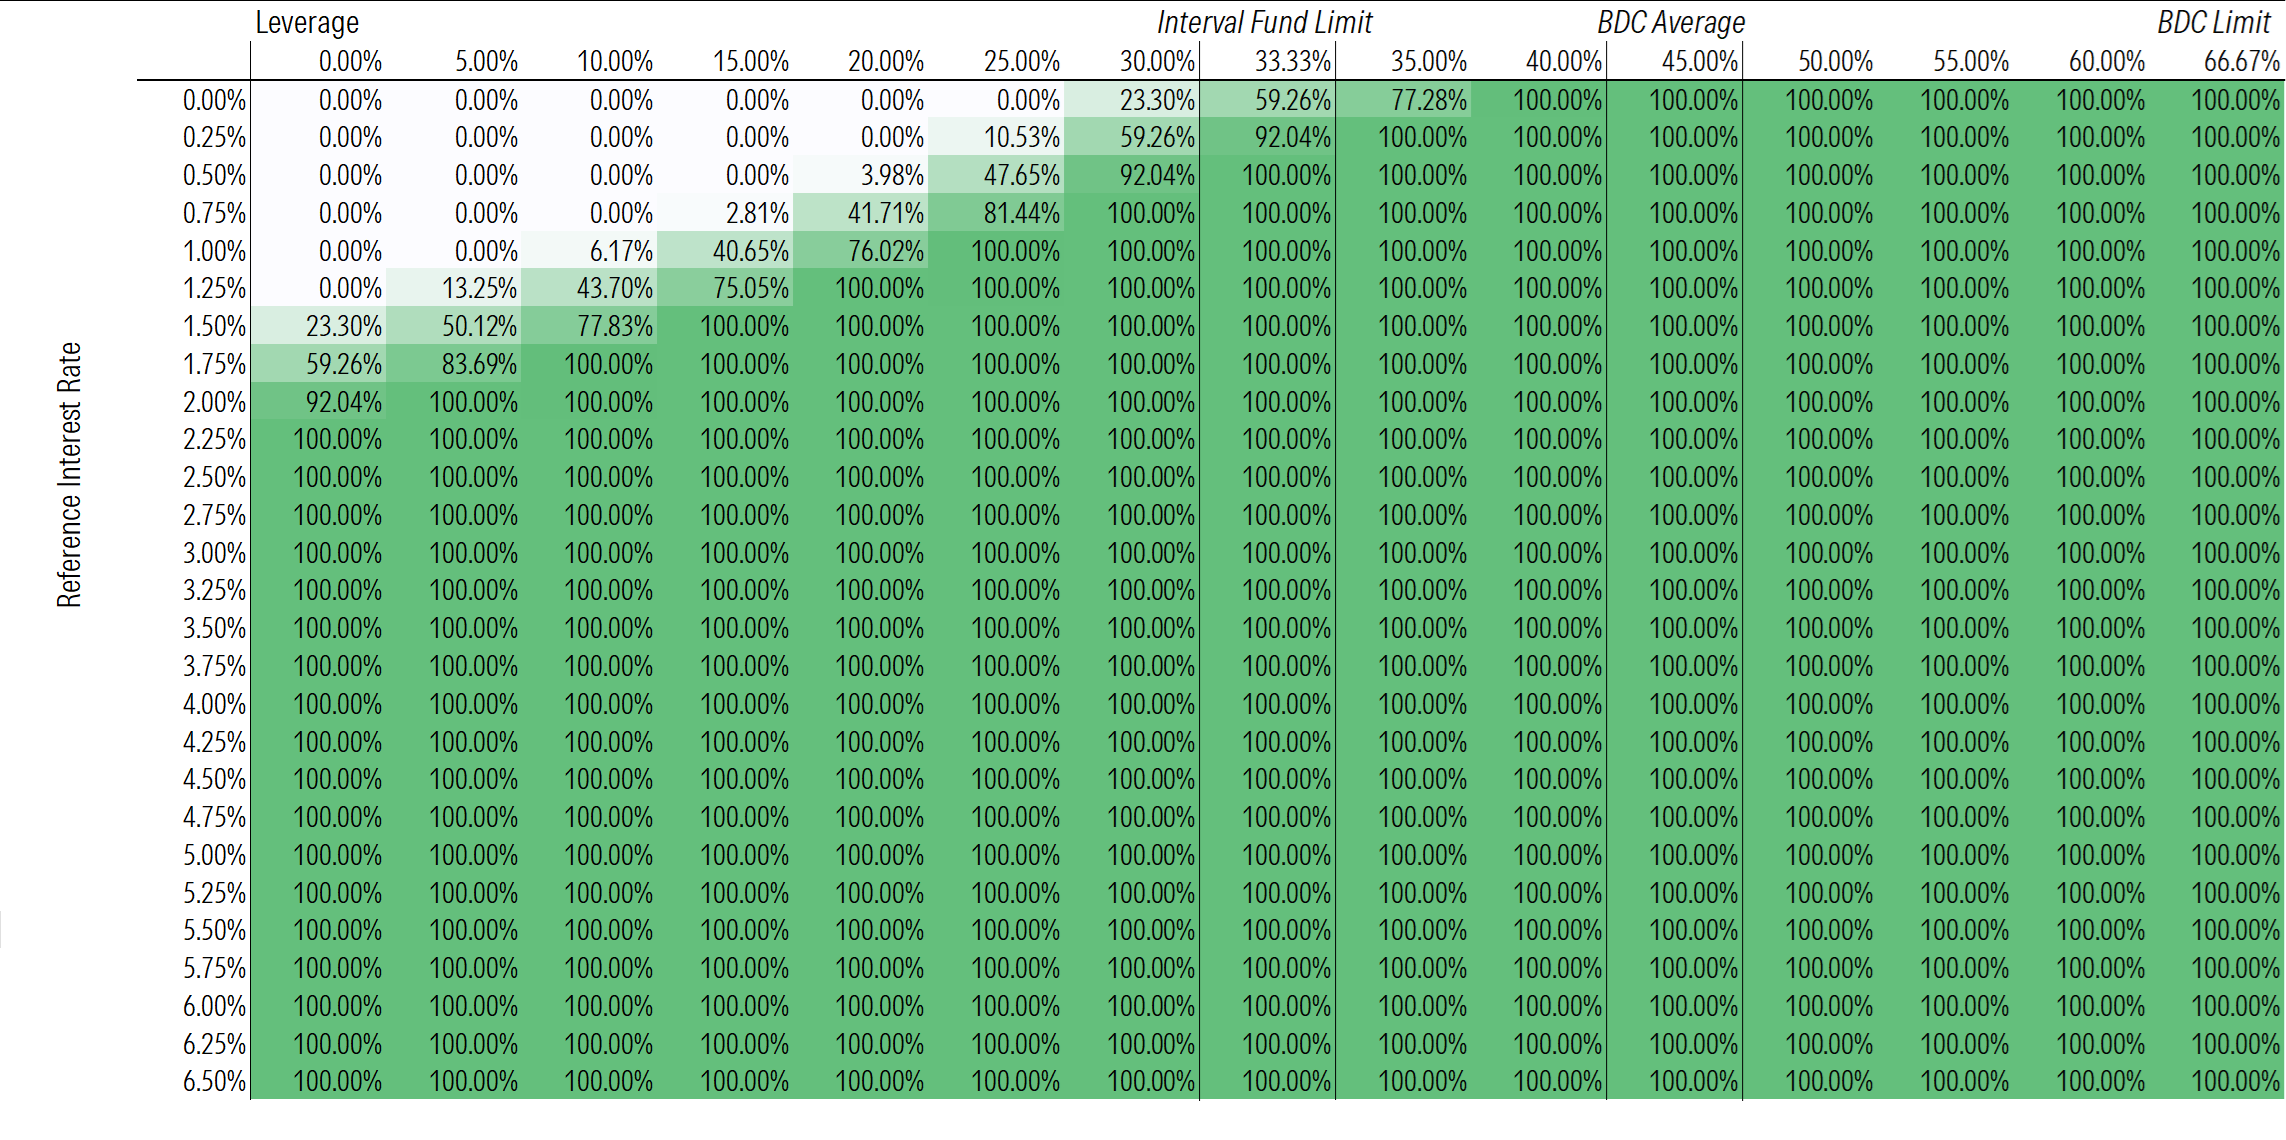
The table above begs the obvious question: What is the “incentive” here? The manager doesn’t control base interest rates, so charging investors more or less based on an uncontrollable variable is not rewarding the manager’s skill. These incentive fees effectively become an additional management fee given these dynamics.
While the table above is a simplified, hypothetical illustration, the real-world data confirms the reality. Consider the universe of listed BDCs, which own many of the same underlying loans as their semiliquid cousins but are generally subject to higher hurdle rates than semiliquid funds. In 2021, a year of historically low interest rates, virtually all of them cleared their hurdles in terms of before-incentive-fee income yields, and they would have cleared them with far greater ease had they been subjected to the common 5% hurdle used by their younger semiliquid cousins. In fact, of the dozen listed BDCs below, half earned more incentive fees than management fees in 2021. Clearly, low interest rates will not pose much of a threat to the collection of these fees.
Despite Historically Low Interest Rates in 2021, Listed BDCs Still Easily Cleared Return Hurdles
Ask Your Advisor These Questions Before Investing in Semiliquid Funds
How to Make Better Fee Comparisons
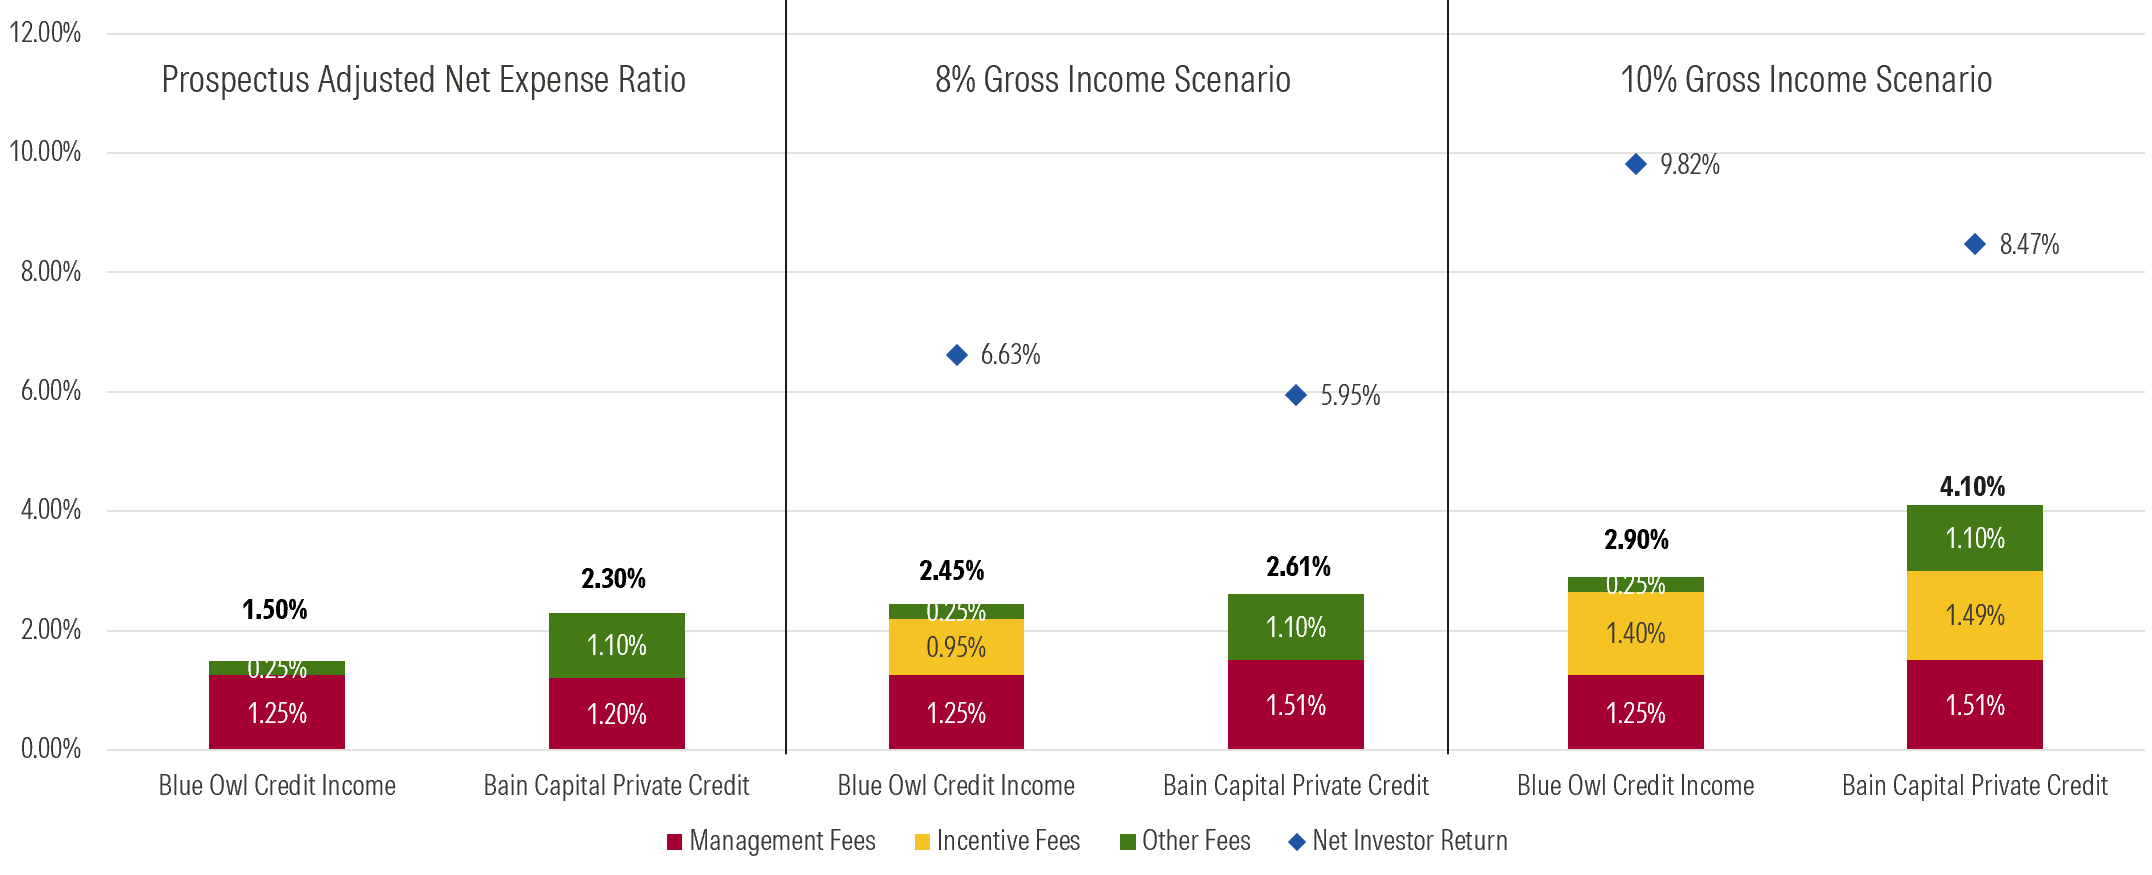
So what is an investor to do? Because of these different fee structures and disclosures, comparing fees across semiliquid funds is difficult, if not impossible, to do simply by looking at filings. To address this, Morningstar is designing a fee methodology to normalize fees across structures based on common gross return assumptions.
The example below applies the method to Blue Owl Credit Income and Bain Capital Private Credit. Blue Owl employs a typical BDC fee structure, while Bain is one of the few BDCs with a unique fee structure. Bain charges a 0.75% management fee on gross assets and a 15% incentive fee over a 7% hurdle. This example shows the fees and net returns under two scenarios: 8% and 10% gross income returns with no capital gains. Investors can use the methodology to better set net return expectations across funds. For instance, they could see how much more Bain would need to return (and thus, how much more risk it would need to take) on a gross basis to match Blue Owl.
Morningstar Fee Normalization: Blue Owl Credit Income vs Bain Capital Private Credit
Fees Always Matter
The price you pay is critical to an investment. Morningstar research has shown time and again that higher-cost products rarely deliver compensatory returns to their investors. With true expense ratios—after accounting for these incentive fees—regularly north of 3.00% annualized (and some much higher), semiliquid funds have an extremely high fee hurdle to clear to beat liquid, public options.
That is not to say they cannot do it. But look at public equity as an example. Just three out of the nearly 300 surviving large-blend Morningstar Category funds outperformed the S&P 500 by 3% or more on a gross basis (that is, enough to cover a 3% expense ratio) over the trailing 10 years through January 2026. It is possible private markets can provide public market-beating returns, but to suggest, as the fees do, that top-1% public market performance is a mere structural feature of private markets seems a bit unrealistic.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States