
7 Key Year-End Tax Strategies to Save Clients Money
Now is the time to lock in savings for tax-year 2024 and beyond.
It’s been a bumpy election season. Investors feel actual and perceived risks from political positioning, policy proposals, and the potential for changes in government. When they react to these risks, they cause temporary volatility in the markets. And this volatility makes investors nervous. Despite all the noise, the standard year-end planning strategies still apply. It’s important to understand and implement these techniques each year, regardless of who’s president. Here are seven important strategies to consider:
1. Capital-Gains-Distribution Avoidance
Now is the time to look at estimated year-end capital gains distributions for your clients’ mutual funds. There’s nothing clients hate more than paying taxes—and it’s even worse if the tax is on phantom income. Whether or not you’re using rebalancing software like Morningstar Total Rebalance Expert, there are certain preliminary steps you must do just to identify where the exposure is. First, identify funds expecting big distributions. You can check the fund companies’ distribution estimates, or go to CapGainsValet (a great service that consolidates all this information). Second, identify an alternative holding that is similar to the fund you’ll be selling that is not estimating a material distribution. Then, identify clients holding a substantial amount of the high-distributing fund. These are the preliminary steps to avoiding big capital gains distributions.
To implement, sell shares in the high-distributing funds and buy the low-distributing alternate funds. It seems easy, right? Unfortunately, you need to be sure that the sale doesn’t result in a material gain (negating the savings from avoiding gains distributions), and that if the sale results in a loss, the replacement fund is not “substantially identical” to the sold fund (triggering a wash sale).
Capital-gains-distribution avoidance can be complicated if not using software like Total Rebalance Expert. The complications can be minimized by focusing on only the high-distributing funds for clients holding a material amount of the funds. No matter how you approach the strategy, it’s important to do it! For example, as of now, we already have funds that will be distributing large amounts. Nuveen Large Cap Select FLRAX is distributing almost 12% of its net asset value and MFS Growth MFEGX is distributing up to 16% of its NAV.
2. Tax-Loss Harvesting
Tax-loss harvesting is an important way to make lemonade out of lemons. If your clients hold positions that have lost money, these can be sold to recognize a tax loss. Again, if you’re not using software, it makes sense to focus only on those positions with material losses. These losses can be used by clients to offset gains and up to $3,000 of ordinary income each year, with excesses carried forward to future years. Losses are disallowed if the positions, or something substantially identical, are bought back within 30 days. Rather than stay in cash and risk missing out on an uptick, it’s best to immediately replace the loss position with something similar but not substantially identical. For example, if selling an S&P 500 index fund, replace it with an actively managed large-cap fund.
3. Tax-Gain Harvesting
Tax-gain harvesting is the opposite of tax-loss harvesting. Why would someone want to harvest gains? If someone is in a low tax bracket, they can actually recognize long-term capital gains and pay zero tax! For 2024, the 0% long-term capital gains rate applies with a taxable income of up to $47,025 if you’re a single filer or up to $94,050 for married couples filing jointly.
As attractive as this sounds, if your client has an IRA, I believe it’s better to do Roth conversions than recognize 0% capital gains. While it might seem like a good idea to claim gains at 0%, if you hold on to appreciated securities until death, the basis is stepped up to fair market value anyway. Recognizing a gain now—even at zero tax—still leaves future appreciation subject to tax should you sell while you’re alive. However, if you’re in a zero to low tax bracket, you can convert IRAs to Roth for a minimal tax cost. This avoids all future tax, even on future appreciation and dividends, avoids required minimum distributions, and heirs can inherit the Roth without having to recognize income. Thus, if you have IRAs and are in a low bracket, it makes more sense to do a Roth conversion than to harvest gains.
4. Charitable Contributions
Most people give to charity by writing checks or charging their credit cards. By using aftertax dollars to get a charitable deduction, the taxpayer essentially breaks even on the contribution. Donating appreciated securities is a better way to go. The donor gets a deduction for the full fair market value and does not recognize gain on the appreciation!
For even more bang for the buck, I’m a big believer in donor-advised funds. A donor-advised fund works like a “charitable IRA.” The donor contributes cash or appreciated securities to the fund and receives an immediate charitable deduction equal to the fair market value of the contribution. The fund can invest the proceeds, which can earn income on a tax-free basis. The donor can then recommend grants from the fund to pay out to qualified charitable organizations. The benefits of a donor-advised funds are many:
- Immediate tax deduction upon contribution to the fund.
- Tax-free earnings within the fund.
- A pool from which the donor can make contributions currently or in the future.
Finally, for clients over age 70-1/2, qualified charitable distributions are a good way to make donations. This strategy works even if your client doesn’t itemize. If people are subject to RMDs, instead of taking part or all of their RMD, they send the IRA funds directly to a charity (not a donor-advised fund). The RMD sent to charity is not taxable, and there is no charitable deduction. However, it does reduce taxable income—and adjusted gross income.
5. Itemized Deductions
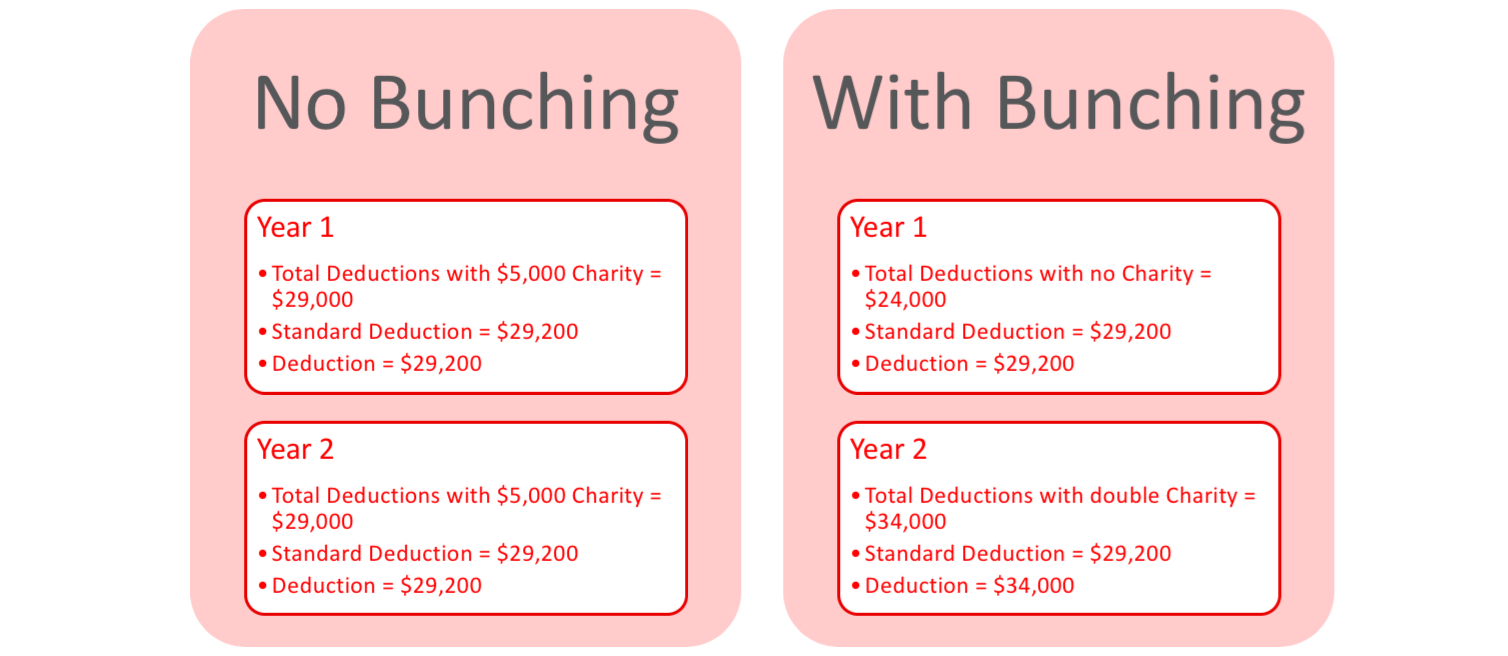
If your client is close to being able to itemize deductions, there’s a strategy that can provide benefits every other year, called “bunching deductions.” Essentially, it’s a way for clients to structure their tax deductions to claim the standard deduction every other year while itemizing the opposite years.
For example, let’s say you have a married couple who typically gives $5,000 a year to charity and their total deductions are $29,000—just under the standard deduction of $29,200. If they bunch their charitable deductions into $10,000 every other year (a donor-advised fund can help spread out what goes to charity), then they itemize with $34,000 of deductions one year and take the standard deduction of $29,200 the other year. This increases their deductions by $4,800 every other year. If they are in the 32% tax bracket, that saves over $1,500!
Bunch-Itemized Deductions
6. Retirement Plan Contributions
Using retirement plans can be a great way to set aside money for the future and get a deduction now. This works best for people who are in a high tax bracket where deferring income makes sense. The contribution limits for 2024 are:
- IRA: $7,000 + $1,000 catch-up over age 50.
- 401(k): $23,000 + $7,500 catch-up.
- SEP IRA/Defined-Contribution: $69,000.
- Defined-Benefit: Contribution determined by actuary. It can sometimes be hundreds of thousands of dollars!
7. Roth IRA Conversions
Roth IRAs are a great strategy for clients, in the right set of circumstances. Amounts converted to Roth will never be subject to future taxes—even on future earnings. Additionally, Roth IRAs are not subject to RMDs, and heirs can inherit Roth accounts tax-free. Roth conversions offer a rare opportunity to pay taxes at a discount.
This year and next are especially attractive for Roth conversions because we have historically low tax rates because of the Tax Cuts and Jobs Act of 2017. As of now, this act expires after 2025.
As stated earlier, for any taxpayer with a year of negative taxable income, it makes sense to do a Roth conversion to the extent that no tax is generated. For those in a low tax bracket, it might make sense to convert an amount that will take full advantage of the lower bracket. For those in higher tax brackets, the decision is not as easy. Please see the chart below for pros and cons.
Pros and Cons of Making a Roth Conversion
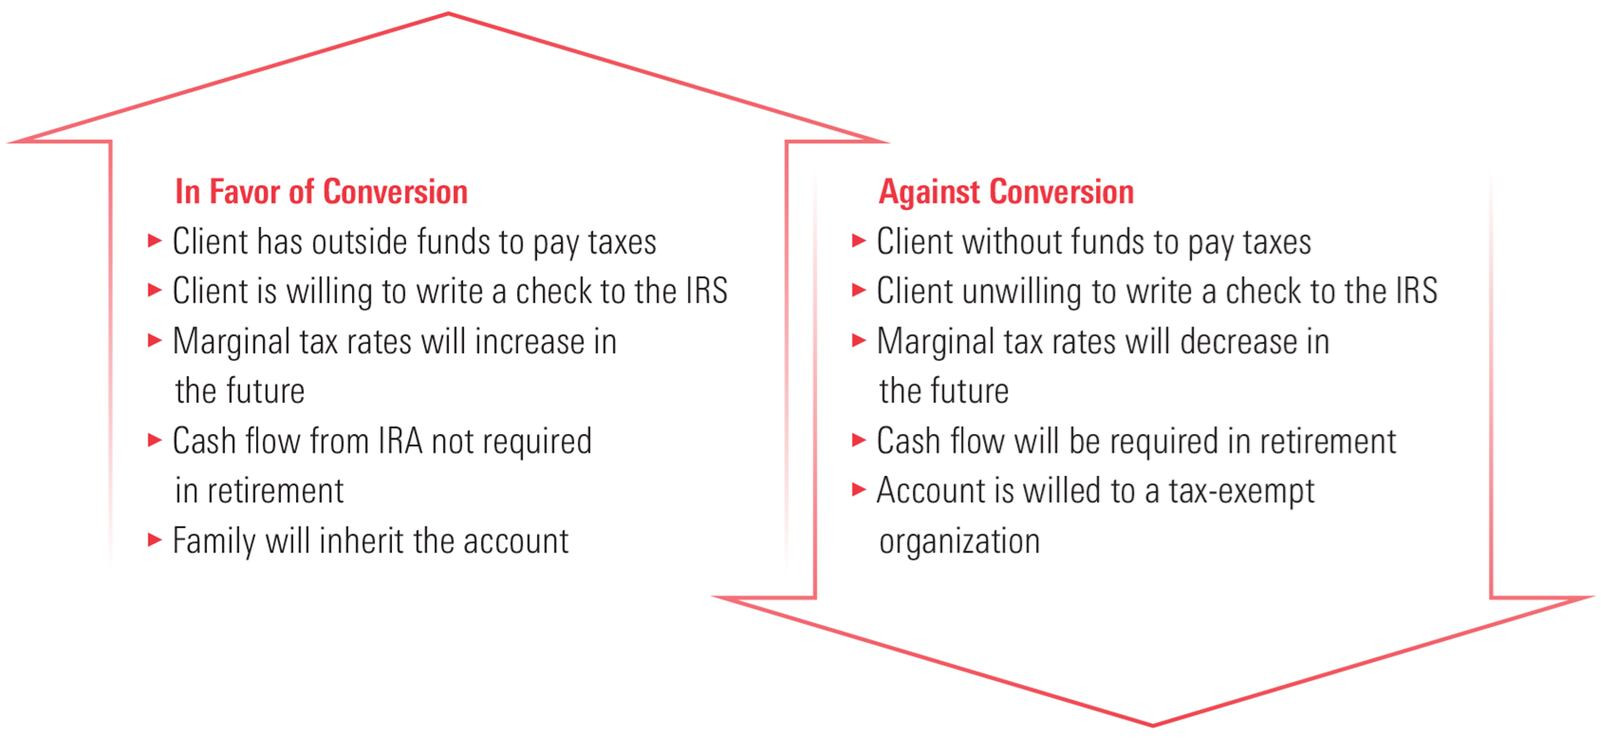
The factors in the “against” column can be stop signs. If there are no outside funds to pay taxes, then converting an IRA to a Roth means withdrawing IRA money to cover the tax payments as well, resulting in additional tax cost. If marginal rates are likely to decrease in the future, it might be beneficial to delay Roth conversion. And if the funds must be depleted over time for cash flow purposes during the retirement years, the immediate tax on the Roth conversion may not be offset by avoiding tax on future growth. Finally, if the IRA is to be left to a charity that won’t owe taxes on the funds, taxes on a conversion won’t be offset by a tax savings later.
Advisors should seriously consider Roth conversion for clients, even for those who were not good candidates in the past. Of course, each client is different, and more detailed tax considerations need to be taken into account, such as impacts on Social Security taxability, surtaxes, and state income taxes. But given historically low tax rates and high market volatility, this might be the time to convert as much as possible to a Roth.
Client Communication
It’s not only important to apply tax savings strategies to clients, but advisors also still need to communicate with their clients—and not just with one email or one newsletter. The advisor needs to continually remind clients about how they are working on their behalf and saving them money. Per Steve Jarvis and the dishwasher rule, “If clients don’t see you doing it, you don’t get credit for having done it.”
Remember to use all your communication tools: webinars, seminars, email, blogs, newsletters, quarterly reports, and meetings!
Election Year Tax Strategies Webinar: Sheryl Rowling, CPA/PFS equips financial professionals with actionable tax-saving strategies tailored for this election year. Sheryl begins by reviewing essential tools in your advisory toolbox, then guides through understanding your clients' unique situations, selecting the appropriate tax strategies, and effective client communication.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.
The opinions expressed here are the author’s. Morningstar values diversity of thought and publishes a broad range of viewpoints.

 United States