
Can AI Chatbots Build a Retirement Portfolio? We Tested Them
A head‑to‑head investing comparison of ChatGPT and Copilot against robo‑advisors and target‑date funds.

Artificial intelligence has dominated headlines over the last few years, for good reasons. It has been compared with the industrial revolution in that it will change the way we do everything and improve our efficiency. Along with predictions about how AI will change the world, there are already industries and jobs threatened by its existence.
Jobs in the financial sector are a prime example of those under threat. Certain AI models have demonstrated their ability to pass all three levels of the CFA exam, an arduous test that many young financial analysts grind through every year. However, AI has yet to replace human analysts who have already passed the exam. Rather, those analysts are encouraged to use AI to be more productive.
But what if the jobs under the greatest threat weren’t performed by humans but a distant cousin of today’s newest technology?
How Robo-Advisors Changed Automated Investing
Robo-advisors first emerged in the 2000s with a push toward automated investing. They grew in popularity thanks to their lower fees and better accessibility than human advisors. They aim to provide investors with a diversified portfolio that is more personalized than just a basic mutual fund or target-date fund.
Robo-advisors usually begin with an assessment to gauge an investor’s goals, time horizon, and risk tolerance. They apply the results to a predetermined framework that selects an asset allocation based on those factors. Robo-advisors can be great for people who want to have a low-cost, hands-off approach to investing.
AI may be new, but it has additional capabilities that today’s robo-advisors have not yet been able to replicate. It can ask follow-up questions to gain more insight or detail, has the potential to consider a wider range of investment options, and is improving every day.
Testing AI Chatbots Against Robo-Advisors and TDFs for Portfolio Construction
To test an AI chatbot’s ability to compete with a robo-advisor, I provided information for two sample investors at different points in their investment lifecycles. The prompts for investors A and B can be seen below.
Investor A, age 25
- I am 25 years old and would like to retire at age 60. I have $10,000 as a starting investment and will add $500 every month until I retire. I would say I have moderate risk tolerance. Build me a diversified portfolio.
Investor B, age 60
- I am 60 years old and want to retire in the next two to five years. My portfolio has a $2 million value, and I will continue contributing $500 every month until I retire. I would say I have moderate risk tolerance. Build me a diversified portfolio.
The investor prompts were provided to two AI chatbots and two robo-advisors. Robo-advisors process information differently from a chatbot. They can make recommendations based on their respective questionnaires but do not have the ability to ask follow-up questions or clarify an investor’s goals or risk profile. They are also generally restricted to a set number of asset allocations. The information provided to the robo-advisors through questionnaires will convey the same investor profile as the information provided to the chatbots. If prompted, a globally diversified portfolio was requested rather than one that focused solely on the US.
I Used Target-Date ETFs as a Benchmark
All recommended asset allocations were benchmarked to a comparable target-date exchange-traded fund. Target-date ETFs are another low-cost option when investing for retirement. They adjust their asset allocation as an investor nears their desired retirement date, so they’re a reasonable alternative to a robo-advisor. Investor A’s recommendations were compared with iShares LifePath Target Date 2060 ETF ITDH. Investor B’s recommendations were compared with iShares LifePath Target Date 2030 ETF ITDB.
How AI Chatbots Compared With Robo-Advisors and TDFs
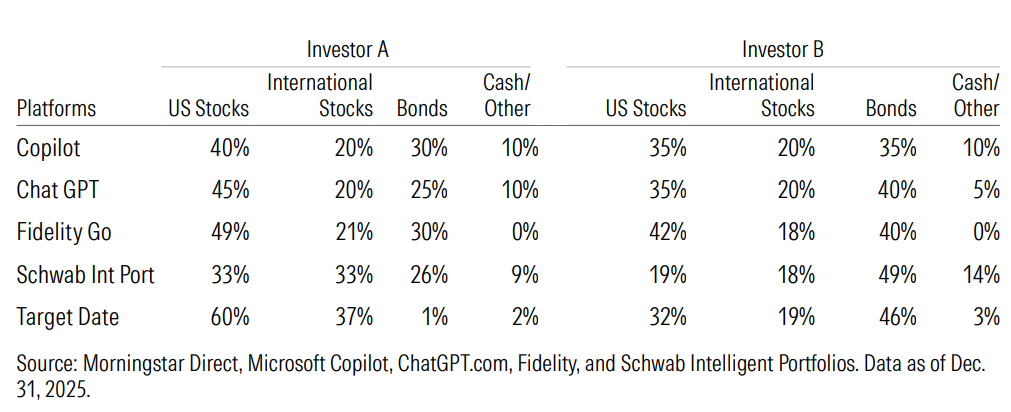
Each platform’s delivery of information differed. So, I summarized the recommendations for an easier comparison in the chart below. It breaks down the asset allocation of each recommended portfolio into four categories: US Stocks, International Stocks, Bonds, and Cash/Other (“Other” includes REITs, alternatives, and money market funds). ChatGPT and Schwab Intelligent Portfolios did not provide specific fund recommendations, but they had a detailed breakdown of stock, bond, and other subcategories. Copilot and Fidelity Go provided specific funds in addition to a broader asset-allocation recommendation.
AI vs. Robo Asset Allocations
The Results for the 25-Year-Old Investor
Patterns emerged across the different recommendations. Investor A’s recommendation was surprisingly consistent across the robo-advisor and AI portfolios. Total stock exposure for each tool ranged from 65% to 70% compared with the target date’s 97% stock allocation. One limitation of target-date ETFs is that they cannot consider investor preferences or risk tolerance. The only information they consider is a target retirement year and balance a standardized portfolio accordingly. For Investor A, the target date would be the riskiest, but likely top-performing, portfolio.
The Results for the 60-Year-Old Investor
Investor B had similar consistency across all recommendations, but Schwab Intelligent Portfolios was an outlier. Schwab’s robo-advisor built the most conservative portfolio by far. It recommended the highest bond and cash allocations while limiting stock exposure to just 37% between US and international asset classes.
The allocation differences for both sample investors can be explained by the weight of information provided. For investor A, both chatbots and robo-advisors were seeking to build a moderate risk level portfolio, and they appeared to succeed at that goal. However, the investor’s age, time horizon, and retirement goals were not prioritized as highly as the moderate risk tolerance, as seen in the moderate portfolios across each recommendation.
My Take on the Portfolios as an Investment Research Analyst
For Investor A, I would argue that each of these portfolios, with the exception of the target-date fund, is too conservative for an investor who doesn’t expect to withdraw money for another 35 years.
For Investor B, I attribute Schwab Intelligent Portfolios’ greater allocation to bonds and cash to the factor that this individual is retiring in a few years. This would create withdrawals and require a reasonably sized cash buffer and/or income engine. The other portfolios aren’t too distinct from Schwab’s, but there’s certainly a noticeable difference.
Should Investors Use TDFs, Robo-Advisors, or AI?
Not all investors want the same thing, nor do they carry the same levels of financial knowledge or awareness of their own risk tolerance. Each of these tools offered an experience for different kinds of investors.
Who Should Use Target-Date Funds
Target-date ETFs are an amazing hands-off approach to save for retirement. They diversify globally and become more conservative as an investor gets closer to the date listed in the fund name. A fund like iShares LifePath Target Date 2060 ETF has 35 years before its investors intend to retire. It therefore takes on more risk than the 2030 version. It is meant for investors who don’t want to check in on their investments.
Who Should Use Robo-Advisors
Robo-advisors offer a more customized allocation than your average target date. They guide an investor to answer questions to gauge time horizon, risk tolerance, and investment experience. These are great tools for someone who may not know where to begin in the investment process.
Done well, robo-advisors help investors open an account, invest responsibly, and manage their assets without having to spend time worrying about the portfolio. However, any robo-advisor will likely be more expensive than a target-date fund as an investor begins to acquire a sizable amount of assets invested. These are great for investors with limited knowledge of financial markets and who are unsure where to begin.
Who Should (Carefully) Use AI Chatbots
Finally, the AI chatbots offered impressively similar recommendations to the robo-advisors. They explained risks, handled portfolio management duties, and provided next steps to guide an investor on what to think about going forward. However, the chatbots are only as reliable as the person using them. Unlike a robo-advisor, chatbots can’t perform transactions to keep an investor’s portfolio on target. AI can be helpful in building a portfolio, but only experienced and confident investors should use it for planning their retirement investments.
Many new investors can be led astray by trying to maximize returns rather than considering their risk tolerance or time horizon. It is possible the chatbot could guide an investor toward responsible investing behavior, but it could also expose them to highly leveraged and risky investments. When the AI tools were prompted to produce a portfolio capable of 20% returns annually, they began discussing options, leverage, and crypto speculation.
The AI tools get credit for presenting the risks associated with these riskier investment choices. But the lack of constraints currently in place for AI introduces additional risks that are not present when using a robo-advisor or target-date fund. It could be a great tool for do-it-yourself investors with experience investing and the means to manage their own portfolios.
Another Key Takeaway: Innovation Brings Risk
Widespread use of AI in wealth management is not a question of if, but how fast. Robo-advisors, target-date funds, and AI assistants each offer unique advantages, but they also carry distinct limitations. While robo-advisors remain a strong option for hands-off investors and target-date funds provide predictable glide paths, AI introduces a new frontier: dynamic, personalized, and interactive guidance without additional fees.
Yet with innovation comes added risk. AI chatbots lack regulatory oversight and can expose inexperienced investors to strategies beyond their understanding. They also require users to execute trades on their own. For now, they serve best as tools for informed investors, not as stand-alone advisors.
As AI evolves, the line between robo-advisors and intelligent assistants may blur, forcing integration between robo-advisors and AI. I hope to see the development of new tools in the near future that combine the best aspects of both for the benefit of investors.
A version of this article appeared in the January 2026 issue of Morningstar ETFInvestor. Click here for a sample issue.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States