
Don’t Fear Long-Term-Care Expenses. Prepare for Them
Nervous about long-term care? Two retirement experts talked with Christine Benz about the fears and realities of this retirement risk, and how to prepare.
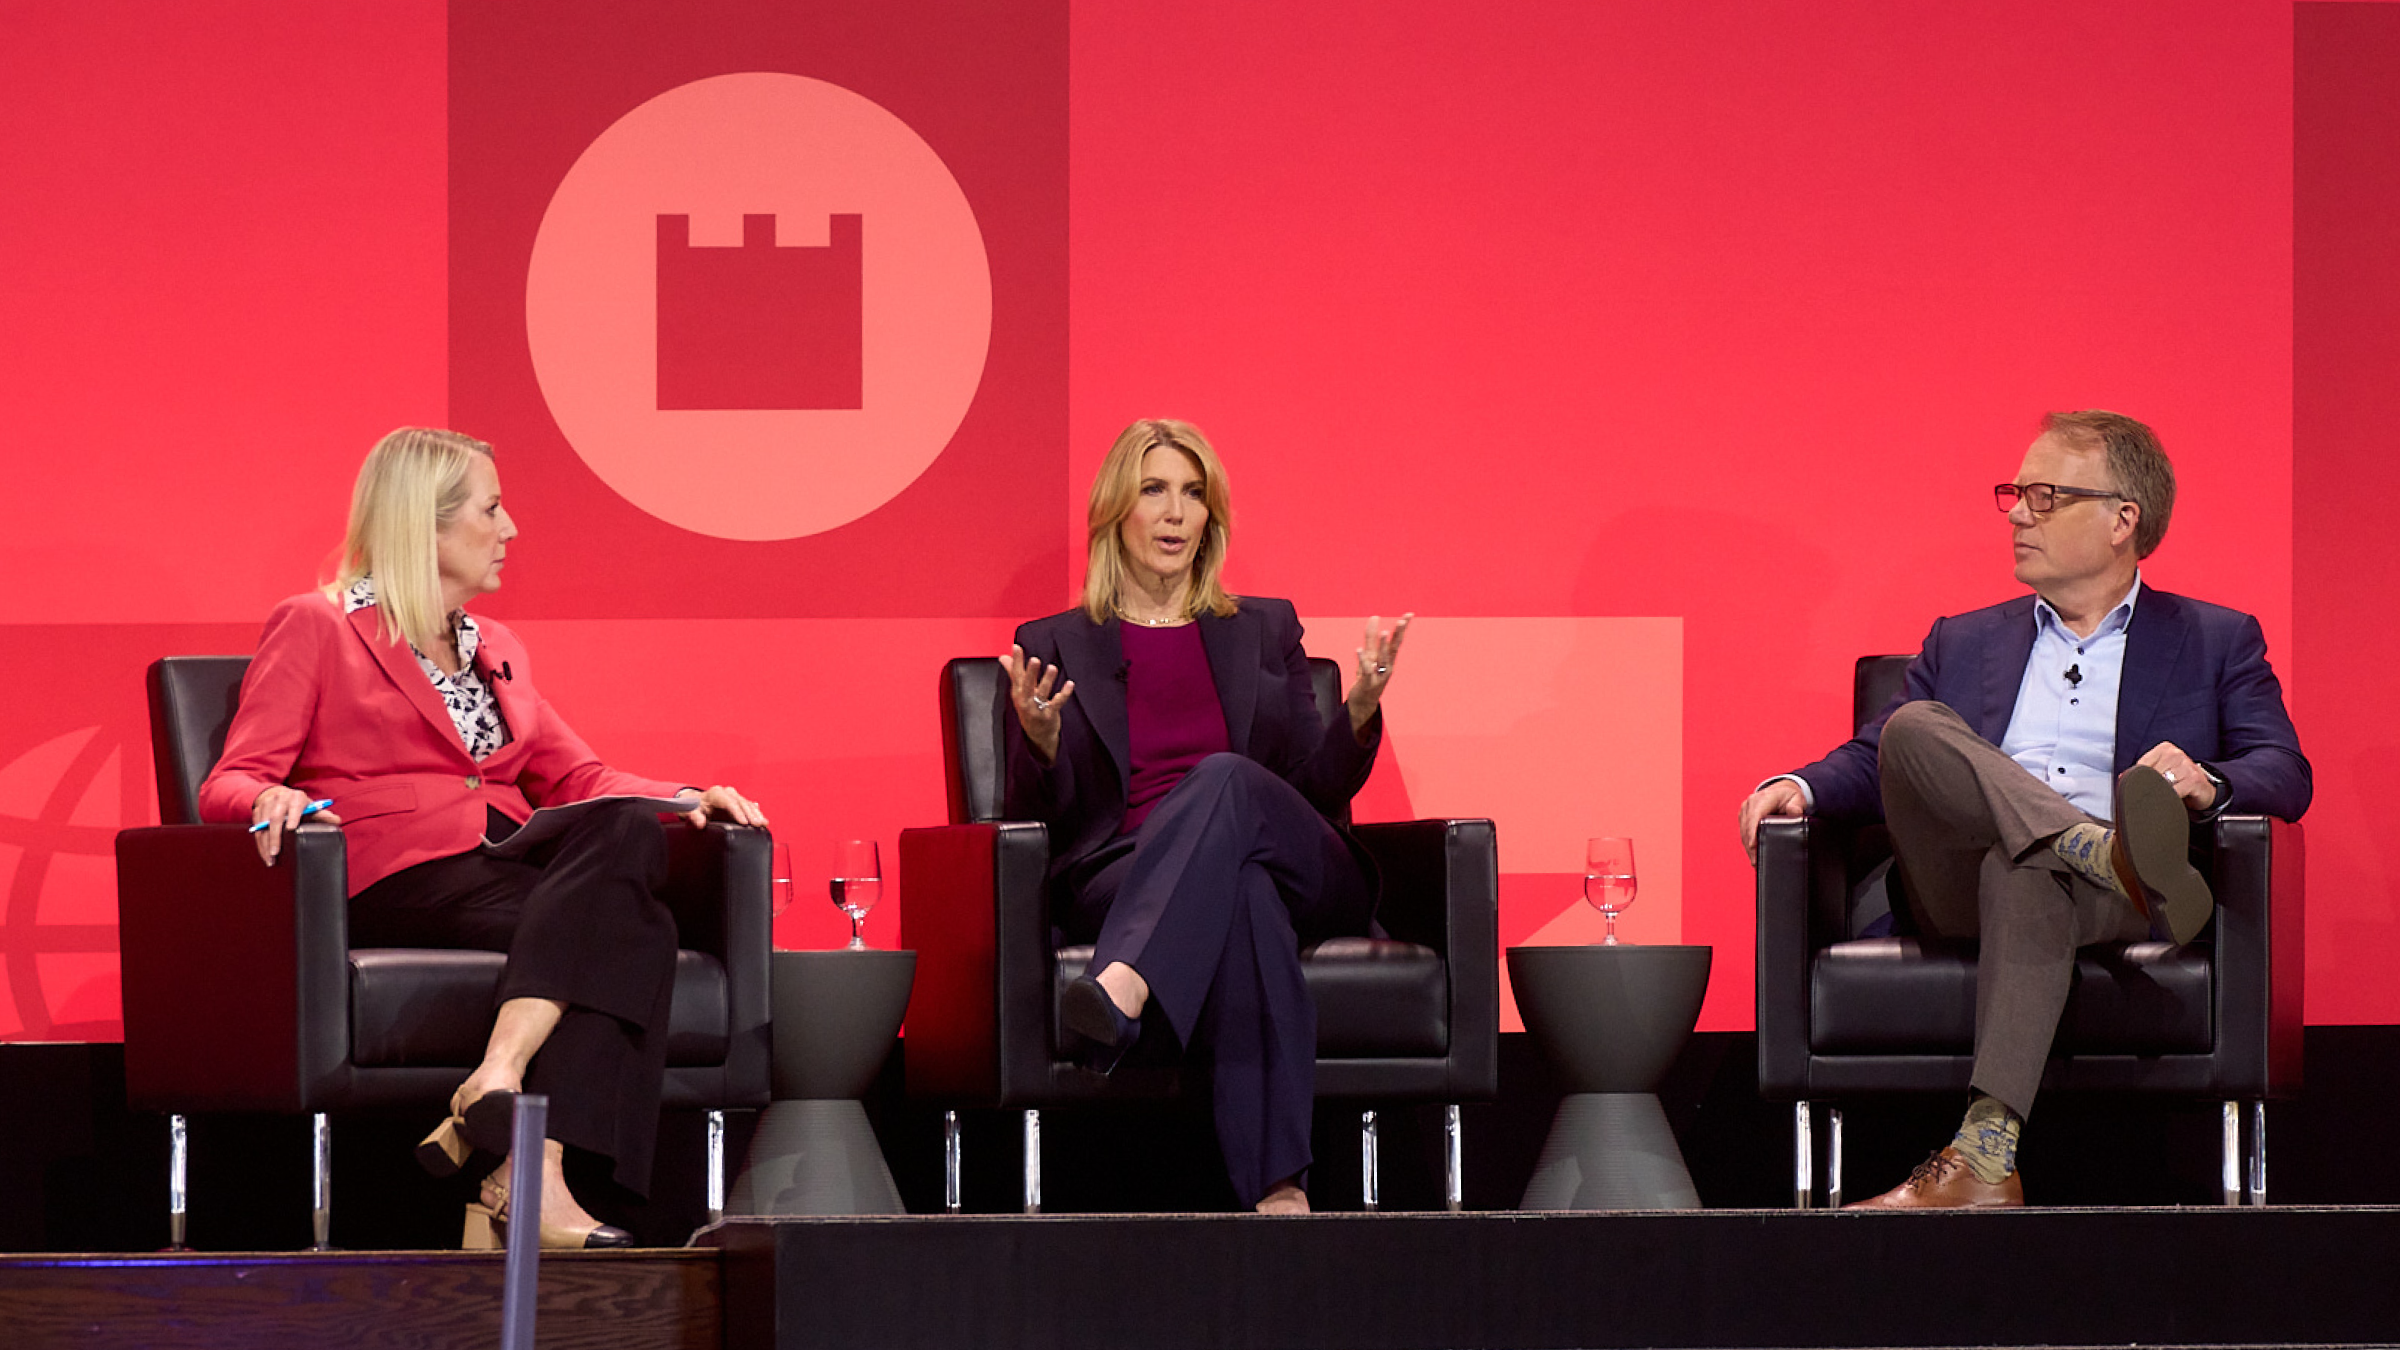
Long-term-care costs, unexpected early retirement, sequence of returns, and inflation can all deliver a shock to your retirement plan, but there are ways to prepare. During a panel discussion at the 2026 Morningstar Investment Conference, I talked about those retirement shocks with Dana Anspach of Sensible Money and Michael Finke of The American College of Financial Services.
Today’s excerpt from that panel focuses on planning for long-term-care costs.
Planning for the Possibility of Long-Term Care
Christine Benz: Let’s stick with that latter stage of life, and a big shock that can occur in many retiree households is having large long-term-care expenses toward the end of someone’s life. I’m wondering if you can both talk about whether you think that contributes to some retirees being reticent or reluctant to spend because they’re worried about having, effectively, a balloon payment at the end of their lives. Dana, can you talk about how you work through this with clients and whether you encourage them to purchase products, insurance products?
Dana Anspach: Yeah. I mean, I think it definitely impacts people’s willingness to spend. There’s that fear that I’m going to have this expensive event later in life and I need to have enough to cover it. We build it into the projections, so we’ll have a particular analysis that stress tests. If a long-term event were to occur at approximately your early 80s, how long would your assets last? And that informs whether we’re going to suggest long-term-care insurance or not. Even if the client can cover a long-term-care event, we’re often bringing it up because the research shows that people who have the insurance are more likely to get quality care. I think that’s a key factor.
You can tend to, particularly later in life, just say, “Oh, I’m going to make do.” And it’s not the time when you really want to make do. If you have the insurance in place and you’ll seek out better care, I think that can be an excellent thing. But I do think it factors into people’s plans even when we’ve stress-tested for it. I think in their mind it’s still this unknown that makes them feel just a little nervous.
Long-Term Care Is ‘an Insurable Risk’
Benz: Michael, what’s your take on the long-term-care insurance product market? It seems like it’s broken in a lot of ways. The pure long-term care; the hybrid policies have come on strong, but how do you think about those types of products?
Michael Finke: First of all, let’s talk about long-term-care risk because this is something where I think there are a lot of misconceptions out there. People say things like, “Well, a huge percentage of us will end up in a nursing home later on in life.” That almost makes it sound like it’s not an insurable risk. We should just save more money for that inevitable thing that’s going to happen. In fact, when you look at the data, you see that it really is an insurable risk in the sense that most people are not going to have a very expensive long-term-care event. Medicare is going to pay for three months; the rest of it can come out of pocket. It’s not going to be that big of a deal, but for some people it’s going to be incredibly expensive. We’re talking more than 10 years in a nursing home, and it has a devastating financial impact on anybody who’s expecting an inheritance, or a surviving spouse.
For them, they need insurance. It is an insurable risk. As you said, it is kind of a broken market. It can be very difficult for people to even obtain long-term-care insurance. We see that many people who bought it end up not keeping it because the price of insurance goes up. I’ve talked to a few advisors who are very knowledgeable about long-term care, and they’re actually more excited about some of these hybrid products than they are about pure long-term-care products these days. By hybrid, we mean long-term care that’s attached to life insurance or an annuity. It can be easier behaviorally to get people to buy some sort of protection against the risk of expensive long-term care through using those types of products. It seems to be a good solution that most advisors should consider.
Valentina Djeljosevic contributed to this article.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States