
How the Cost of Long-Term Services and Supports Shapes Retirement Readiness
Omitting LTSS costs distorts retirement outcome projections.
The population of the United States is aging: The number of Americans aged 65 and older is projected to surge from 56.1 million in 2020 to 80.8 million in 2040.
As the population of older Americans grows, demand for long-term services and supports—a broad range of services to assist individuals who have trouble with activities of daily living—will almost certainly increase.
For many retirees, LTSS might be the most significant risk to retirement-income adequacy.
In our new report, my colleague Jack VanDerhei and I study the financial impact of needing LTSS, using the Morningstar Model of US Retirement Outcomes. We calculate the percentage of households simulated to run short of money in retirement under two scenarios: one that includes LTSS costs, and a counterfactual where LTSS costs are excluded.
The results are striking. When LTSS costs are included, 41% of households are projected to run short of money in retirement—compared with just 26% when those costs are excluded.
The picture is clear: Ignoring LTSS costs presents an overly hopeful view of retirement readiness. In reality, these costs could pose a major financial risk—one that should not go ignored.
Projected LTSS Needs and Costs for Baby Boomers
To understand why LTSS costs have such a large effect on retirement outcomes, let’s start by discussing how likely someone is to need care and what it might cost. (We are only focusing on baby boomers in this section.)
To conduct this analysis, we used a framework that estimates health statuses over time. For example, a household member might be projected to require in-home healthcare or move to a nursing home.
Overall, we found that about 43% of baby boomers will need LTSS in retirement.
While this might seem like a very high number, these estimates are comparable (and are actually lower in some cases) to other studies. For example, a study by the Urban Institute found that 48% of adults surviving to age 65 will receive some type of paid LTSS.
We also explored how LTSS risk varies with longevity, estimating the likelihood of incurring LTSS costs in retirement by age at death. Intuitively, we found that the likelihood of needing LTSS increases with longevity. These estimates are detailed on the chart below.
Percentage of Baby Boomers With LTSS Needs in Retirement by Death Age
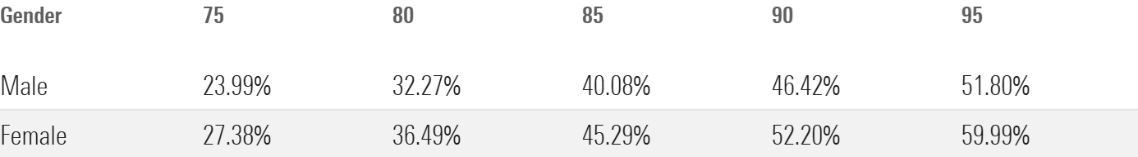
These results show that longevity risk and LTSS risk are interconnected. Households should consider both together rather than thinking about each risk in isolation.
Next, we calculated the present value of LTSS costs, based on our state projections and cost figures from Genworth’s Cost of Care Survey. These estimates are the costs that a household would have to pay to avoid spending down to qualify for Medicaid-financed LTSS or relying on charity.
We report both unconditional and conditional costs. Unconditional costs represent LTSS costs for all households, regardless of whether they need LTSS. The conditional costs reflect the expenses for households that were simulated to need LTSS.
Present Value of LTSS Costs From Retirement Age Through Death for Baby Boomers
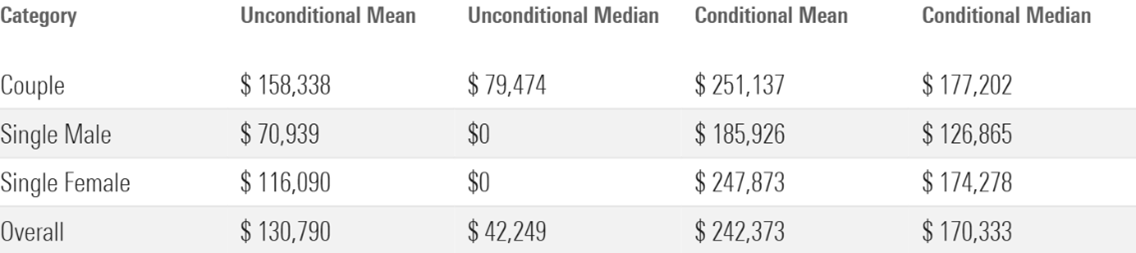
The results reflect the skewness in the distribution of LTSS needs.
It is notable that the unconditional median for single men and single women is $0, which shows that, in at least half of the cases, no paid LTSS is needed. However, when LTSS is required, the costs can be substantial. For example, the annual median cost for a room in a nursing home is currently over $100,000, per Genworth.
LTSS’ Impact on Retirement Outcomes Across Demographic Groups
Now that we have discussed the cost and likelihood of needing LTSS, we’ll focus on our analysis of retirement outcomes across demographic groups.
Intuitively, the percentage of households projected to have adequate resources for retirement declined significantly when LTSS costs were included—across every dimension in our analysis.
The exhibit below contains the results by family status. The largest decline was for single females, with 52% projected to be at risk of falling short in retirement when LTSS costs are included, compared with 34% without LTSS costs. Significant decreases were also observed for couples (37% to 22%), single males (36% to 23%), and all households in aggregate (41% to 26%).
Percentage of Americans Aged 20-Plus With Retirement-Funding Ratio Less Than 1 by Family Status With and Without LTSS Costs
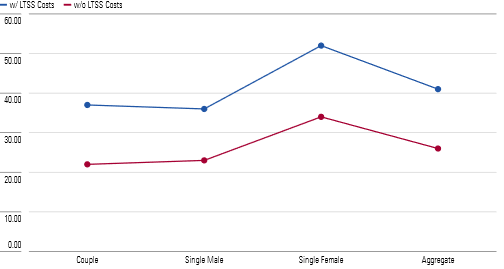
The largest decrease occurred for single women because women have longer life expectancies than men, which increases the risk of needing LTSS. The impact is not as pronounced for women who are part of a couple because couples tend to have more resources than single women.
The next exhibit shows results by age cohort. The biggest decrease in the percentage at risk of retirement shortfalls occurred for Generation Z, with the share at risk dropping from 41% with LTSS costs to just 21% without. Millennials also saw a large drop—from 42% to 24%. The decreases were smaller for Gen X and baby boomers.
Percentage of Americans Aged 20-Plus With Retirement-Funding Ratio Less Than 1 by Age Cohort With and Without LTSS Costs
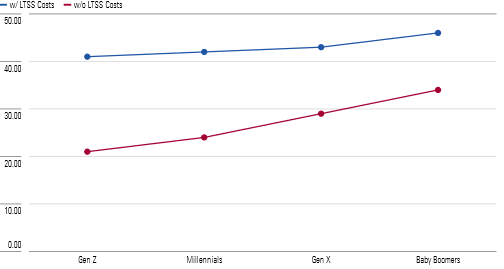
The larger decreases for Gen Z and millennial age cohorts are due in large part to the compounding effects of LTSS inflation. We model LTSS costs growing at a faster rate than price inflation, and the longer time horizon for Gen Z and millennials amplifies the cost differential compared with those closer to retirement.
We also investigated retirement outcomes with and without LTSS costs by race and ethnicity and income level. These results and more can be found in the full report.
The Value of LTSS in Retirement Planning
LTSS are a critical but often overlooked risk to retirement-income adequacy.
Our research shows that ignoring LTSS costs in retirement outcome projections leads to materially different conclusions. Moreover, our analysis demonstrated that longevity risk and LTSS risk are closely linked, as those who live longer are more likely to need LTSS. These results underscore the importance of planning for LTSS in retirement.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States