
How Guaranteed Lifetime Withdrawal Benefits Work
GLWBs provide lifetime annuity income, while allowing you to control your assets.

Survey after survey shows that retirees want lifetime income.
Income annuities—products that convert a lump sum balance into a stream of income cash flows—deliver just that, which is why they are widely considered one of the most efficient ways to generate retirement income.
But they come with a catch: Once you annuitize (that is, convert the balance into income payments), there is no undo option—the money is locked up in the product.
That’s where a guaranteed lifetime withdrawal benefit comes in. A GLWB is an insurance feature wrapped around assets within a “savings annuity”—my preferred term for any annuity with an account balance. GLWBs provide lifetime income without requiring the purchaser to give up control of their assets. However, these products require a long-term mindset and careful attention to the fine print.
Below, I walk through the key details to understanding GLWBs. Importantly, I am not going to be discussing savings annuities (which include fixed-rate, fixed index, variable, and registered-index linked) in detail here.
For more on the fundamentals of savings annuities, as well as income annuities, refer to my recent piece.
How Much Guaranteed Income Do You Need in Retirement?
An Overview of GLWBs and How They Are Determined
As I wrote earlier, a GLWB is an insurance feature wrapped around a savings annuity. Unlike with income annuities, the savings annuity account balance is not annuitized. This means the purchaser is not irrevocably exchanging a lump-sum insurance premium for a guaranteed income stream. Instead, when the purchaser decides to start taking withdrawals, the insurer calculates the lifetime withdrawal benefit: the amount that can be withdrawn from the savings annuity for the rest of the purchaser’s life, even if the account balance falls to zero.
One of the main benefits of a GLWB is that it allows the owner to retain control of the account balance. The owner can withdraw more than the guaranteed amount at any point in time.
However, excess withdrawals lower or reset the guarantee. Further, in many cases, the amount of guaranteed income with a GLWB is less than what is offered with an income annuity.
GLWBs often come with an explicit insurance charge—typically a percentage of the benefit base (I explain the benefit base below)—assessed annually. But the cost may also be embedded in the rates and terms offered, particularly for fixed index annuities, where caps, spreads or participation rates can be adjusted to help fund the guarantee.
Payout Rates
The insurer determines the GLWB amount by multiplying the “payout rate” and the “benefit base.” The payout rate is a percentage (for example, 5%) that the insurance company specifies in the contract. The payout rate depends on what age the owner starts taking withdrawals and whether the guarantee is based on a single life or two lives. GLWB payout rates tend to increase at older ages and decrease if the guarantee covers a couple rather than an individual.
The exhibit below demonstrates a hypothetical payout rate table.
Hypothetical GLWB Payout Rate Table
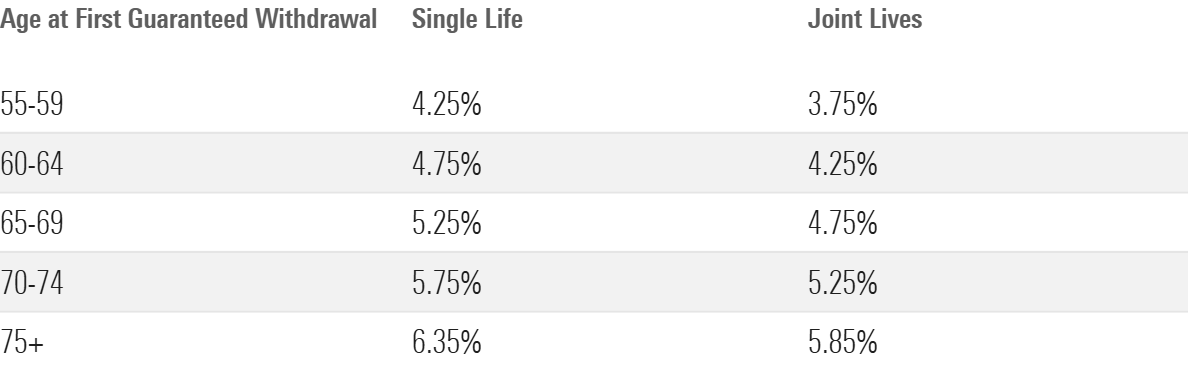
Benefit Base Designs
The benefit base can be thought of as a hypothetical balance that the insurer uses to calculate the GLWB amount.
The benefit base is typically floored at the premium payment less withdrawals. Some GLWB designs provide a “ratchet” or “step-up” feature, in which the benefit base is stepped up to the account balance of the savings annuity if it is greater than the benefit base (this typically occurs at the contract anniversary).
Some designs provide a guaranteed minimum roll-up. With this feature, the benefit base is guaranteed to increase annually. The roll-up is typically calculated via a simple interest or via a compound interest method. In most cases, the roll-up rate is a fixed number (for example 7%), but it can also be variable. The latter approach is increasingly common with fixed index annuities, where the benefit base roll-up rate is equal to the credited interest rate times a bonus multiplier. I discuss this design in detail in my research report on fixed-indexed annuities with a GLWB.
In addition to roll-ups and ratchets, some contracts offer a deferred bonus that boosts the benefit base. For example, the benefit base might increase by 200% of the first-year premium as long as the owner does not take a withdrawal in the first 10 years.
The exhibit below demonstrates the benefit base increase functionality under an annual ratchet, and a simple interest rate roll-up design on a hypothetical variable annuity contract. While I present them separately to illustrate how they work, they may be combined in practice. Also, while I chose to use a variable annuity for this example, the benefit base mechanics are similar or the same when a GLWB is added to other types of savings annuities.
Illustration of GLWB Benefit Base Designs

Note: I assume $100,000 is contributed to the variable annuity. Under the simple interest rate roll-up, the benefit base is guaranteed to increase by 7% of the initial premium each year. I chose variable annuity subaccount returns to illustrate the benefit base increase mechanisms. The VA account balance fluctuates based on the performance of the underlying subaccounts.
The next exhibit contains two calculations of the insurance benefit based on the two prior exhibits.
- The first example assumes that an individual bought a variable annuity with a GLWB with the simple interest rate roll-up feature when they were 55 years old. Now at 65 years old, they have opted to start guaranteed withdrawals.
- In the second example, everything is the same except that they bought the variable annuity when they were 65 years old and are starting withdrawals when they are 70 years old.
Sample Calculation of GLWB Amount for Single Life

Note: The numbers I used for this example were reasonable at the time of the publication of the annuity guide. However, payout rates, GLWB benefit base roll-up rates, and other features vary with the level of interest rates and other factors in the capital markets.
As illustrated above, the GLWB benefit is often fixed once guaranteed withdrawals start. However, with some designs, the guaranteed withdrawal amount can increase over time or start at a higher level before decreasing once the underlying account balance has been depleted.
Using GLWBs for Retirement Income
A partial allocation to a GLWB can provide meaningful lifetime income and may help mitigate against both market and longevity risk. When used thoughtfully, it can complement other retirement income sources while preserving flexibility.
When considering a GLWB, it’s critical to focus on what is contractually guaranteed. Promotional language may highlight the upside potential, and while there can be a lot of value there, the core value of a GLWB lies in the lifetime income floor it provides.
Moreover, while GLWBs offer ongoing liquidity and flexibility, it is easy to use the products suboptimally. For example, taking large withdrawals can shrink the insurance benefit and cashing out entirely (the industry refers to this as “surrendering” or “lapsing”) eliminates the guarantee, meaning the owner paid for protection that was never actually used. From an economic perspective, the GLWB’s value is typically highest when the contract is held for life and withdrawals are managed within the rules of the guarantee.
My perspective is that a partial allocation to an annuity with a GLWB can improve retirement outcomes for some investors. But adding a GLWB doesn’t eliminate the need for thoughtful asset allocation elsewhere: In fact, the remaining portfolio may need to tilt more toward equities or other higher-risk assets to maintain overall balance.
GLWBs can be structured in a variety of ways. And as with any retirement income solution, it’s important to evaluate a GLWB in the context of your overall portfolio to ensure it complements broader asset allocation and income goals.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States