
Is the Saver’s Match the Key to Closing the Retirement Savings Gap?
Our projections show the new program can significantly boost retirement wealth.


The retirement savings gap between higher- and lower-income households is well-documented. The real question is, what can the industry do to close the gap and help investors be better prepared for retirement?
Enter the Saver’s Match.
This federal program was created as part of the Secure 2.0 Act of 2022. Starting in 2027, it will provide eligible savers a 50% match on the first $2,000 of qualified retirement contributions (where eligibility is based on modified adjusted gross income). Given the bipartisan support behind Secure 2.0, it is fairly unlikely that the new presidential administration will seek to reverse this initiative.
In our new report, my colleague Jack VanDerhei and I analyzed the impact of the Saver’s Match on retirement wealth for a representative sample of Generation Z and millennial workers. We used the Morningstar Model of US Retirement Outcomes to simulate the program’s effects under four behavioral scenarios.
Overall, we found that savers eligible for the full match could experience significant increases in retirement wealth, with percentage increases hitting double digits in many cases. Further, the best outcomes occurred when eligible individuals changed their savings behavior to take full advantage of the program.
Effective promotion and education will likely play a key role in encouraging broader participation. Government efforts, along with outreach by plan sponsors, will also help maximize the program’s impact.
How We Assessed the Impact of the Saver’s Match
To analyze the impact of the new program, we built the program’s features into our simulation framework. We also created behavioral scenarios, which assume that eligible individuals start saving or save more to get the full match.
Scenario Assumptions

We compared the Saver’s Match scenario runs with our status quo results. Specifically, we calculated wealth ratios, defined as the ratio of projected wealth at retirement under a Saver’s Match scenario over projected wealth at retirement under our status quo scenario.
For example, let’s say a household’s projected wealth at retirement age under a Saver’s Match scenario is $110,000 in a particular simulation trial. When compared with $100,000 in the baseline for the same household and simulation trial, the wealth ratio would be 1.1. We then converted the wealth ratio into a percentage increase by subtracting one—meaning that for the example above, the percentage increase would be 10%.
Single Women Will Tend to Benefit More From the Saver’s Match Than Single Men and Couples
When analyzing the impact of the Saver’s Match for single males, single females, and married couples, we found that a much larger portion of single women will be eligible for the match than single men or couples.
Specifically, about 43% of single women will qualify, compared with about 35% of single men and 30% of couples.
Moreover, single women often see a larger percentage increase in wealth at retirement than other groups, as demonstrated below. This makes sense given the well-documented gender wage gap and gender retirement savings gap.
Mean Percentage Increase in Wealth at Retirement From Status Quo Results for Gen Z and Millennial Males, Females, and Couples Qualifying for the Full Match

Non-Hispanic Black Americans and Hispanic Americans Stand to Gain the Most From the Saver’s Match
We also looked at the impact of the Saver’s Match across race and ethnicity groups. We noted that a much larger proportion of non-Hispanic Black and Hispanic Americans will qualify for the match than other groups.
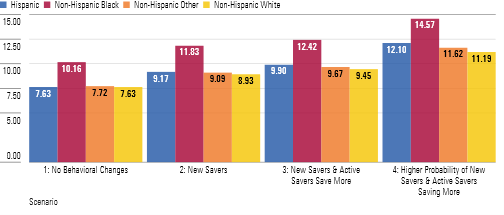
Our calculations show that 48.9% of Hispanic American households and 43.5% of non-Hispanic Black households will qualify for the program (full or partial match) compared with just 25.6% and 28.7% for non-Hispanic Other and non-Hispanic white households, respectively.
Shifting focus to the percentage increase in wealth at retirement, we found that non-Hispanic Black Americans will see the largest increases in wealth at retirement across all the scenarios, as demonstrated below. Hispanics will also see larger gains than other groups in many cases, though the change is not as large.
Mean Percentage Increase in Wealth at Retirement From Status Quo Results for Gen Z and Millennials Qualifying for the Full Match by Race and Ethnicity
Conclusion
In sum, our research showed that the Saver’s Match could substantially boost retirement wealth for eligible savers, with percentage increases reaching double digits in many cases. Moreover, single women, Hispanic Americans, and non-Hispanic Black Americans stand to benefit disproportionately.
While we did not discuss this finding here, the full report shows that workers in industries prone to higher retirement-income inadequacy, such as agriculture and retail, are expected to see larger wealth increases compared with peers.
The analysis clearly shows that the biggest improvements in wealth occurred in the scenarios where eligible individuals started saving or saved more to get the full federal match.
The government and the retirement industry’s promotion of the program is critical for maximizing its impact. Plan sponsors, in particular, can make a meaningful difference by providing targeted communication aimed at low- to moderate-income workers who might qualify.
This article was generated with the help of automation and reviewed by Morningstar editors. Learn more about Morningstar’s use of automation.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.
Morningstar Investment Management LLC is a Registered Investment Advisor and subsidiary of Morningstar, Inc. The Morningstar name and logo are registered marks of Morningstar, Inc. Opinions expressed are as of the date indicated; such opinions are subject to change without notice. Morningstar Investment Management and its affiliates shall not be responsible for any trading decisions, damages, or other losses resulting from, or related to, the information, data, analyses or opinions or their use. This commentary is for informational purposes only. The information data, analyses, and opinions presented herein do not constitute investment advice, are provided solely for informational purposes and therefore are not an offer to buy or sell a security. Before making any investment decision, please consider consulting a financial or tax professional regarding your unique situation.

 United States