
Will the Retirement Savings for Americans Act Save Retirement?
Morningstar’s analysis shows that most Americans would be better off under the status quo.

Roughly 50% of Americans do not have access to a retirement plan through their employer.
The Retirement Savings for Americans Act, introduced in Congress in October 2023, aims to close that gap. In particular, the RSAA would create a federal retirement plan, automatically enrolling workers without access to an employer-sponsored plan at a 3% savings rate. The RSAA would also provide a federal match tax credit for low- and moderate-income workers that would begin to phase out at median income.
While the proposal may sound promising, our research shows that most Americans would be better off under the current system.
Why? In short, the RSAA would likely change both investor savings behavior and retirement plan sponsor behavior, resulting in lower net savings rates.
How We Set up the Study
We analyzed the impact of the RSAA using the Morningstar Model of US Retirement Outcomes. We built the RSAA’s features into the simulation, auto-enrolling workers who were simulated to not have access to an employer-sponsored defined-contribution, or DC, plan into the federal retirement plan.
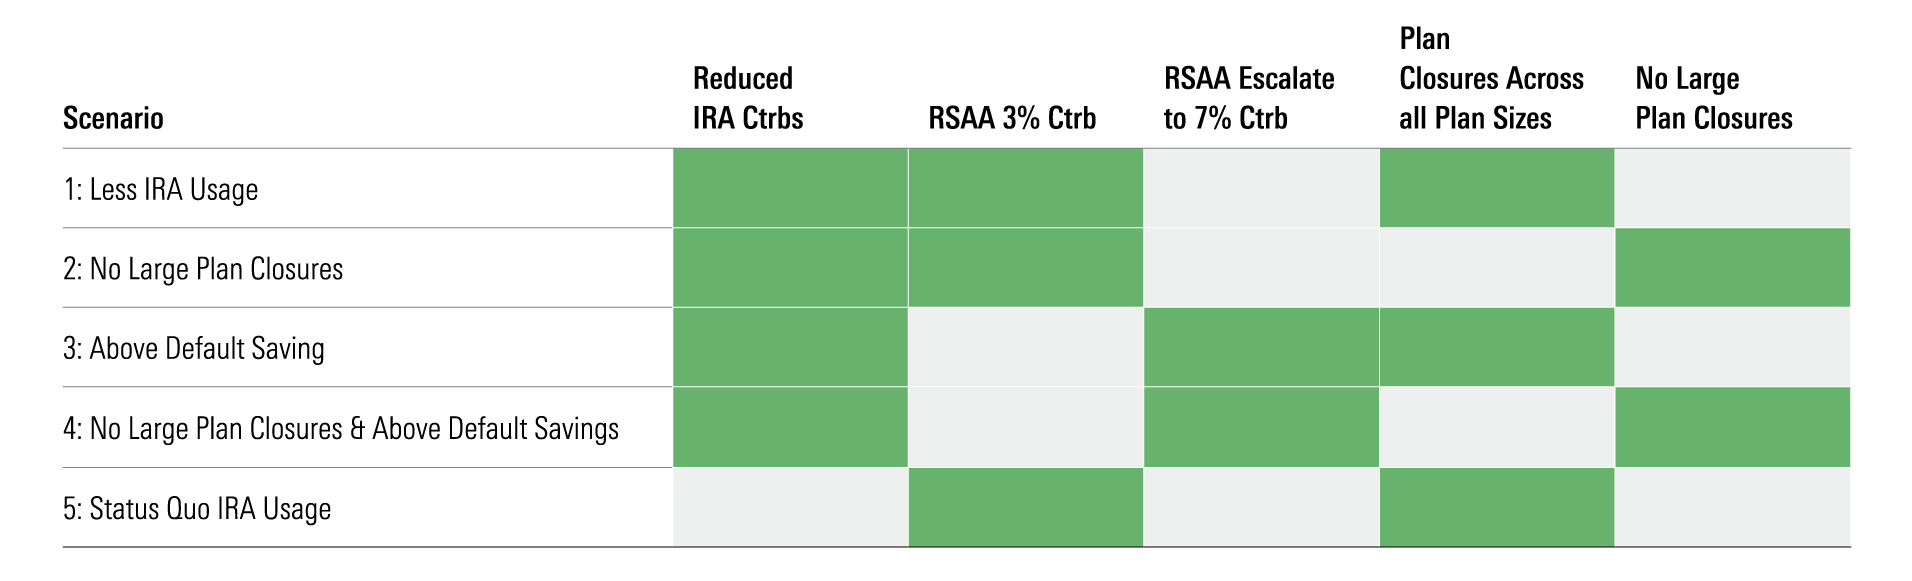
We created five scenarios that reflect potential but realistic changes to investor savings behavior and retirement plan sponsor behavior in response to the enactment of the RSAA. While no scenario is intended to represent the most likely outcome, the impact is likely to fall somewhere in the range. (We touch on some of the scenario assumptions when we discuss the results but refer to the full report for more detail).
Scenario Assumptions
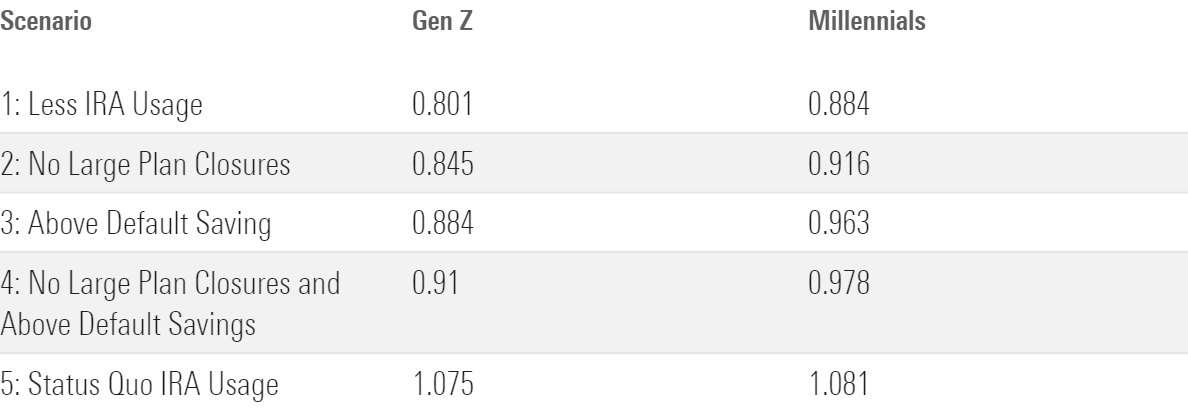
We compared the RSAA scenario runs to our status quo results. Specifically, we calculated wealth ratios, defined as the ratio of projected wealth at retirement under a hypothetical RSAA scenario over projected wealth at retirement under our status quo scenario. A wealth ratio less than 1 indicates that the RSAA scenario tested led to a decrease in the wealth balance.
In Most Plausible Scenarios, the Majority of Working Americans Would Be Better Off With the Status Quo
The results from our analysis paint a clear picture of the RSAA leading to less wealth at retirement in four of our five scenarios for both the Gen Z and millennial age cohorts.
Median Wealth Ratios by Age Cohort
We also analyzed the impact of the RSAA when controlling for income and race and ethnicity. We found that, in both cases, the RSAA would likely lead to less wealth than the status quo. The full paper contains the specific figures.
There are many factors contributing to why the RSAA would reduce the resources available to Americans at retirement.
One key reason is our assumption that the RSAA would lead to fewer employers sponsoring DC plans. We made this assumption because, for many employers, maintaining their plan would not make sense from an economic perspective as the government would effectively fund employer contributions for workers earning around median income or less. (We vary this assumption by the size of the employer; refer to the full paper).
This matters because savings rates for those who participate in an employer-sponsored DC plan are significantly higher than the RSAA’s 3% default. For instance, the average deferral rate in Vanguard’s “How America Saves 2024” report was 7.4%. Notably, even workers earning less than $50,000 per year had deferral rates of 5.1% or more.
The gap in the savings rate remains when considering matching and nonelective contributions, as the federal match tax credit is comparable to what many employers offer in the private sector. Additionally, employer matches for DC plans do not phase out for workers earning more than the median income level. Thus, for many workers, including those earning less than the median income, participation in an employer-sponsored DC plan would result in larger overall contributions than the RSAA federal plan.
When we assume workers save up to 7% per year (scenarios 3 and 4), there is a smaller shortfall compared with the status quo. However, because there is no auto-escalation feature with the RSAA plan, the majority of workers are likely to save at the default rate.
Another factor is the impact of the RSAA on IRA saving behavior. In all but the “Status Quo IRA Usage” scenario, we model a lower probability of contributing to an IRA. This assumption is based on the observation that people are more likely to save in IRAs when they do not have access to an employer-sponsored retirement plan, and workers would likely consider the RSAA federal account as equivalent to such a plan.
Beyond savings behavior, we simulated workers opting out of the RSAA plan, meaning that some workers who are auto-enrolled do not participate and save. We also modeled preretirement withdrawals, which reduce the balance in the RSAA plan.
Who Would the RSAA Help?
While the RSAA would make things worse in aggregate, we noted that the proposal would boost outcomes for workers simulated to not participate in an employer-sponsored DC plan in the future. This is an intuitive finding, as this is the main goal of the bill. However, we also noted that outcomes were significantly worse for workers who would have otherwise participated in a DC plan for a large portion of their careers.
Median Wealth Ratios by Number of Years of Future Participation in a DC Plan in Status Quo

Conclusion
In sum, our research shows that most Americans would be better off under the status quo. Moreover, our results highlight the importance of ensuring that policy changes do not harm retirement savings behavior.
For a more detailed explanation of the topics discussed in this article, refer to the full report.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States